
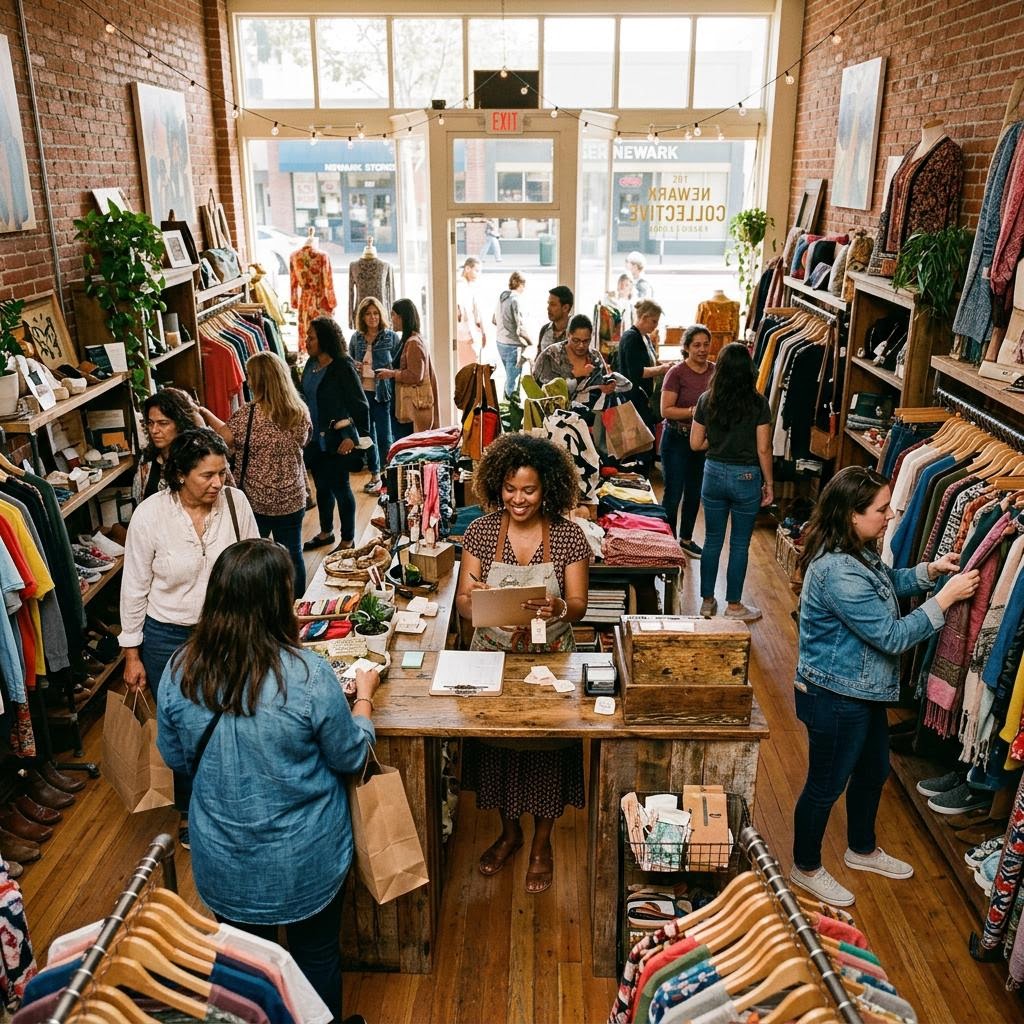
Operating a retail storefront in Newark, California, is a high-wire act of inventory management, merchandising, and customer experience. Whether running an independent clothing boutique, a specialized hobby shop, or a local home goods store, retail owners must constantly anticipate what their customers will want weeks or months before they actually walk through the door. This requires purchasing inventory upfront, tying up massive amounts of cash in products that may take a full season to sell.
When the retail environment is stable, businesses can manage these cycles with traditional lines of credit or careful cash flow planning. However, retail is rarely perfectly stable. An unexpected opportunity to purchase high-demand inventory at a steep discount, a sudden breakdown of a critical Point-of-Sale (POS) system, or the need to rapidly execute a marketing campaign for a local event can create urgent capital demands. When traditional bank loans are too slow or inaccessible, some Newark retailers explore a Merchant Cash Advance (MCA) to secure immediate liquidity.
Retail-Specific Capital Pressures in Newark
Retailers in Newark face a unique set of capital pressures driven heavily by seasonality and fixed overhead. Rent for a highly visible commercial storefront must be paid regardless of whether foot traffic is surging during the holidays or dragging during the slow summer months. The fundamental challenge of retail is that capital leaves the business in large, immediate chunks (buying seasonal inventory, paying commercial rent), but returns in small, incremental amounts (daily customer credit card swipes).
Because modern retail relies almost entirely on credit and debit card transactions, the daily revenue stream is highly visible and highly variable. A sudden shift in the local economy, or even a week of severe weather, can drastically suppress daily sales, leaving the business struggling to cover immediate obligations. It is precisely this reliance on daily credit card volume that makes retailers the primary candidates for—and targets of—merchant cash advances.
How a Merchant Cash Advance Generally Works
It is imperative for Newark retailers to understand that a Merchant Cash Advance is not a traditional business loan. It is a commercial transaction in which a funding provider purchases a specific dollar amount of the business's future sales at a discount. The MCA provider delivers a lump sum of cash to the retailer upfront, often funding the account relatively quickly of approval.
In exchange, the retailer agrees to remit a fixed percentage of their daily credit card batches (or overall daily bank deposits) to the provider. This automatic daily sweep continues until the original advance, plus a predetermined markup known as the 'factor rate,' is fully collected.
The defining feature of an MCA is that the daily payment amount fluctuates directly with sales volume. On a busy Saturday where the retailer processes $5,000 in credit card sales, the MCA provider collects a larger dollar amount. On a slow Tuesday where sales only hit $500, the provider collects a smaller dollar amount. This structure ensures the payment scales with the business's daily reality, which is why it is often marketed heavily to the retail sector.
Uses of Funds and Urgent Scenarios
Because an MCA is one of the most expensive forms of commercial capital, it must be deployed strategically. It is not designed to fund long-term structural changes, such as buying the building or executing a complete, multi-month store remodel. Using an MCA for long-term investments will likely choke the business's cash flow.
Instead, an MCA should be used tactically to solve immediate crises or to capture fleeting, high-margin opportunities.
- Purchasing a massive, unexpected shipment of high-demand inventory at a steep supplier discount that expires in 48 hours.
- Funding an emergency repair to the store's physical infrastructure, such as a broken storefront window or a failed HVAC unit during extreme weather.
- Executing a rapid, highly targeted marketing campaign leading up to a major local Newark event or holiday weekend.
A Newark, California Retail Scenario
To ground this concept, consider a hypothetical scenario involving an independent specialty apparel and gear shop in Newark, California. It is late October, and the owner learns that a major, highly anticipated community festival will be hosted in a nearby plaza in three weeks. The owner knows this event might drive significant foot traffic past their storefront, but their current inventory is too low to capitalize on the surge.
The owner needs $20,000 immediately to place a rush order for high-margin, festival-specific merchandise. A traditional bank loan would take weeks to underwrite, causing the owner to miss the inventory shipping deadline. Instead, the owner applies for a Merchant Cash Advance.
The MCA provider reviews the shop's strong, consistent daily credit card processing history and might approve an advance shortly after. The owner immediately wires the funds to the supplier, receives the inventory in time, and has a record-breaking sales weekend during the festival. Over the next several months, the MCA provider automatically sweeps a set percentage of the shop’s daily credit card sales until the advance and the factor fee are paid. The owner determined that the high cost of the MCA was justified because the gross profit from the festival inventory far exceeded the fee of the advance. (Note: This is an illustrative example meant to explain the mechanics of an MCA. Actual factor rates, approval speeds, and terms vary widely by provider.)
Qualification and Documentation Preparation
The underwriting for an MCA focuses almost exclusively on the velocity and consistency of a retailer's cash flow, rather than historical profitability or pristine personal credit. The provider needs to know that the business processes enough daily credit card volume to support the daily sweep.
Newark retailers must provide the last several months of business bank statements and merchant processing statements. The provider will analyze these to ensure there are no frequent negative days or excessive bounced transactions. The documentation is minimal, which is what enables the rapid funding timeline.
Cash-Flow and Payment Considerations (Tradeoffs)
The speed of an MCA comes at a severe premium. Providers use a factor rate rather than an APR. Because this fixed total repayment amount is typically collected rapidly over a few months based on daily sales, the effective annualized interest rate can be exceptionally high.
The most dangerous tradeoff is the relentless daily impact on gross cash flow. The MCA provider takes their percentage before the retailer can use that money to pay rent, employees, or suppliers. If a Newark retailer operates on a 15% net margin and gives up 10% of their daily gross sales to an MCA, the business is left with virtually no breathing room. Furthermore, paying off an MCA early rarely results in cost savings, as the total repayment amount is fixed.
Comparison Questions and Responsible Next Steps
MCAs require extreme caution and rigorous mathematical analysis before signing. Newark retailers must ask the provider direct questions: What is the exact total dollar amount that must be repaid? What specific percentage of daily sales will be withheld? How is the collection processed (split at the terminal or ACH sweep)? Is there a reconciliation clause if sales drop dramatically due to unforeseen circumstances?
An MCA is not universally appropriate and should be viewed as a last resort or a highly tactical tool for high-margin opportunities. By carefully comparing alternatives and aggressively modeling the daily cash flow impact, Newark retail owners can protect their margins while securing the urgent capital they need.