
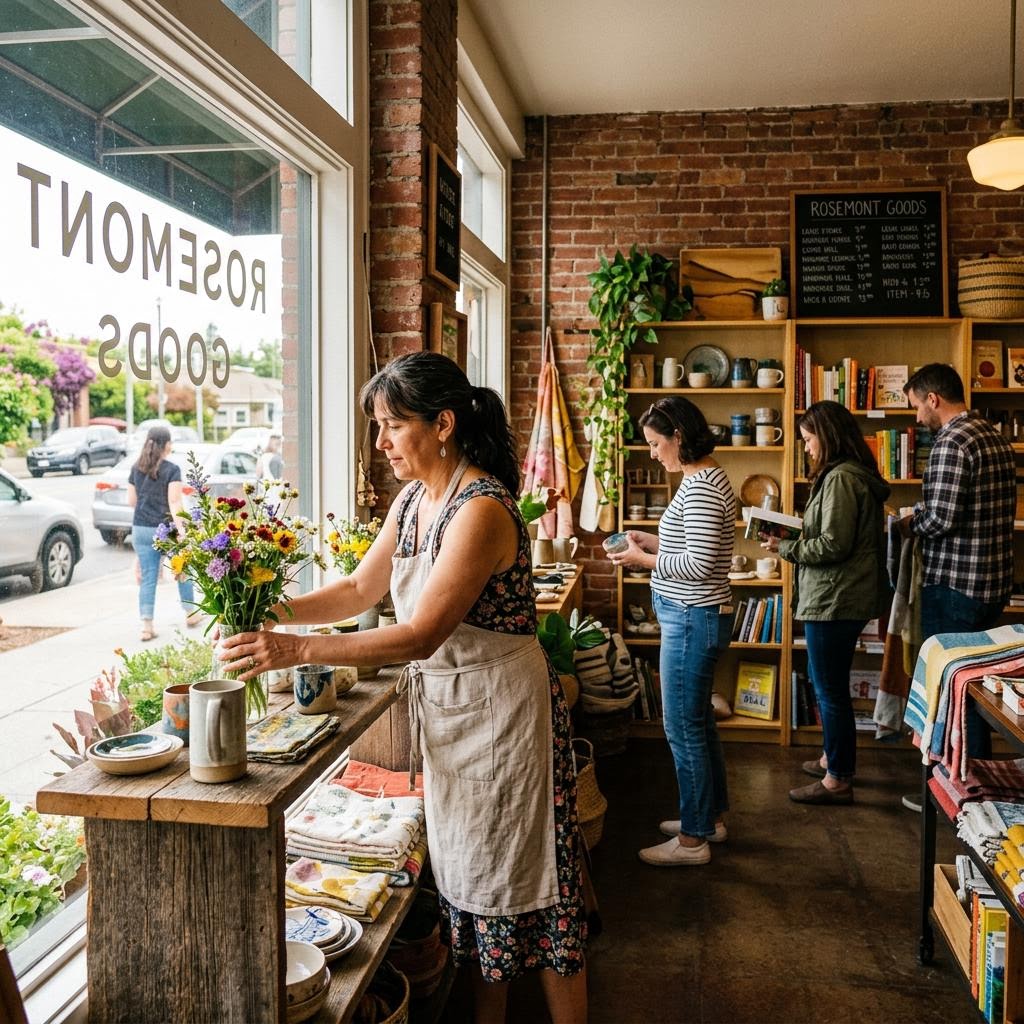
Retail operations in the Rosemont area of Newark face a distinct set of operational demands. Managing a physical storefront requires constant attention to inventory levels, seasonal foot traffic, staffing, and the ever-present need to maintain an appealing retail environment. The financial reality of retail is that you must spend money to make money—often months before the revenue is actually realized.
Whether you are stocking up for the holiday rush, renovating your shop to improve the customer experience, or managing the slow months of late summer, having access to the right type of capital is essential. For Rosemont retailers, the goal is to utilize funding strategically to smooth out cash flow and capitalize on growth opportunities without carrying unnecessary debt burdens.
The Rosemont Retail Landscape
Assessing the Rosemont area for a retail storefront means evaluating the specific balance of neighborhood accessibility and commercial visibility a property might offer. Local retailers must ask whether they will be serving a community base that prioritizes convenience or one that seeks localized curation. Businesses aiming to succeed must invest time in verifying the actual foot traffic rhythms and buying habits of their prospective customers.
However, running a retail business in Newark involves high fixed costs. Rent for a visible storefront, utilities, insurance, and base payroll remain constant regardless of whether you have a record-breaking sales week or a completely stagnant one. When you layer the variable costs of purchasing inventory on top of these fixed expenses, the pressure on daily cash flow becomes evident.
When entering a funding discussion, it is crucial to demonstrate how your business operates within this specific landscape. Showing a clear understanding of your local customer acquisition costs and your seasonal sales patterns proves that you are managing the business proactively, not just hoping for foot traffic.
Managing Inventory Cycles
Inventory is the lifeblood of any retail operation, but it is also the largest trap for cash. To have the right products available when customers want them, you must purchase goods from suppliers well in advance. This creates a massive cash flow gap: the cash leaves your account in September, but the revenue does not return until November or December.
Working capital loans and lines of credit are frequently used to bridge this exact gap. A revolving line of credit provides the liquidity to place large orders with suppliers, taking advantage of bulk discounts. Once the seasonal inventory sells, the line is paid down. This allows the business to scale its purchasing power without draining the cash needed for daily operations.
It is vital, however, to ensure that the inventory you purchase is actually going to sell. Taking on debt to buy dead stock compounds the problem. Smart retailers use historical sales data to inform their financing needs, ensuring they only borrow what they can confidently turn into revenue.
Storefront Upgrades and Point-of-Sale Technology
The physical experience of a retail store is a major competitive advantage over e-commerce. A well-lit, organized, and aesthetically pleasing shop in Rosemont encourages longer visits and larger purchases. Renovating the space, upgrading shelving, or investing in new signage can drive significant returns.
Similarly, modernizing your Point-of-Sale (POS) system and inventory management software can drastically improve operational efficiency. These upgrades require upfront capital.
- Use term loans for major renovations, amortizing the cost over several years to match the expected lifespan of the improvements.
- Consider equipment financing for specialized shelving, lighting systems, or high-end POS hardware.
- Calculate the expected return on investment—will this renovation increase daily foot traffic or average transaction value?
Navigating Seasonality
Almost all retail businesses experience seasonality, and Rosemont is no exception. While the holiday season is universally recognized, many businesses have secondary peaks related to back-to-school, summer, or local events. Surviving the 'shoulder seasons'—the slow months between the peaks—requires discipline.
A common mistake is taking on a merchant cash advance during a slow month to cover rent, assuming the next busy season will effortlessly pay it off. While sometimes necessary, this can severely compress the profit margins of your busy season. A better approach is securing a line of credit during your strongest months, ensuring you have access to cheaper capital when things slow down.
Preparation is the antidote to panic. By mapping out your annual cash flow projections, you can identify exactly when the bank account will dip and arrange for working capital proactively.
E-commerce Integration and Expansion
Many successful physical retailers in Newark are discovering the necessity of an omnichannel approach. Integrating a robust e-commerce platform with your Rosemont storefront allows you to reach customers beyond the immediate neighborhood and offers convenient local pickup options.
Building a professional e-commerce presence—including website development, digital marketing, and the logistical setup for shipping and fulfillment—is a project that requires dedicated funding.
- Determine the upfront cost of the digital build-out versus the ongoing costs of digital marketing.
- Ensure your inventory management system can handle dual channels before launching.
- Seek a term loan or utilize a working capital line to fund the initial push, mapping the debt service against projected online sales.
Organizing for the Ask
When you approach a lender to finance your retail business, they are primarily evaluating your ability to move inventory and generate consistent cash flow. You must be prepared to present clean, organized financial data.
Have your profit and loss statements, balance sheets, and tax returns readily available. Be prepared to discuss your inventory turnover ratio—how quickly you sell and replace your stock. Lenders look favorably on businesses that do not have capital tied up in aging, unsellable goods.
Additionally, clearly articulate the 'Use of Funds.' If you need $50,000, explain exactly how much is allocated to Q4 inventory, how much to the new window display, and what the expected impact on gross revenue will be. Clarity builds confidence.
A Strategic Foundation for Retail
For retail owners in the Rosemont area, business loans should be viewed as strategic tools to manage timing and facilitate growth, rather than lifelines for fundamental profitability issues. The right capital structure allows you to buy aggressively, merchandise beautifully, and operate smoothly.
By taking the time to understand the different funding options available—whether it is a term loan for a build-out, a line of credit for inventory, or equipment financing for a POS upgrade—you can make financial decisions that strengthen your business.
Focus on aligning the cost and duration of the capital with the specific project it is funding. With a measured approach to debt, your Rosemont retail store can build a resilient foundation for long-term success in Newark.